The Working Paper · assurance · Amsterdam
Not every request for assurance calls for an audit.
An investor, bank or buyer wants comfort about your figures. Which engagement that calls for can differ by tens of thousands of euros. We start with that question rather than with the heaviest answer.
request a call: Sophie Terwindt RA replies within one working day · call: for a quick question
No tax advice, no payroll, no bookkeeping. One discipline, and therefore no interest in a heavier engagement than you need.
Our audit approach comes out of big four practice: six years at Deloitte, on audits of multinational and listed companies under IFRS, US GAAP and PCAOB standards. We apply that method at our scale.
Every file is reviewed by a registered accountant with signing authority — not passed down, not signed off at a distance.
01
How much assurance does your situation call for?
Four levels, from a full audit down to factual findings. Most companies that approach us need a lighter engagement than the one they came asking for.
assuranceVoluntary audit NV COS 700 series / ISA 700 → The highest level of assurance we provide. For companies without a statutory audit requirement whose investor, bank or buyer expects audited financial statements. Limited
assuranceReview engagement NV COS 2400 / ISRE 2400 → Lighter and cheaper than an audit. Often sufficient where the requesting party wants comfort rather than full assurance. Factual
findingsAgreed-upon procedures NV COS 4400N / ISRS 4400 → No opinion, but precisely defined procedures on specific balances. The right answer when a single subject is in question. Required
by lawStatutory audit take the audit requirement check → If you are subject to statutory audit, a Wta-licensed firm signs it. We prepare that audit. The check tells you within a minute whether it applies to you.
02
What you get from us
We regularly recommend something lighter than what was asked for. It costs us hours and saves you money — and it is why people come back.
Scope, planning and expectations are fixed before work begins, including those of shareholders and investment committees.
How we scope an engagement, which level of assurance fits, how we set materiality and how a fee is built — all of it is published here.
03
Are you actually subject to statutory audit?
The answer determines whether we can carry out your engagement ourselves or prepare you for someone else's. Many companies discover the obligation in the second year, when it already applies and their opening balance has never been audited.
04
What you are probably wondering
How do I know which engagement I need?
By asking what the other party actually wants to see. An investor who says "audited figures" often does not mean an audit — a review engagement is frequently enough, and sometimes only a single balance is in question.
That difference is substantial in cost. It is the first question we ask in an introductory call, and we regularly recommend a lighter engagement than the one requested.
Can the firm perform our statutory audit?
No. A statutory audit may only be performed by an audit firm holding a Wta licence from the AFM, and The Working Paper does not hold one.
If you are subject to statutory audit, another firm signs and we prepare you for it. If you are not, we can carry out the assurance engagement ourselves.
Why a specialist firm rather than a full-service accountancy practice?
Because we do not sell tax advice, payroll or bookkeeping, and therefore have no interest in a longer relationship than the engagement warrants.
In practice it means every file is reviewed by a registered accountant rather than passed down, and that our independence is simpler to protect than at a firm that also keeps your books.
We already have an accountant. Why approach you?
We do not replace your accountant. If they perform your statutory audit, we prepare your organisation for it — which makes their work faster and your invoice lower.
If an investor or bank separately asks for assurance, that can be a standalone engagement we carry out.
What does it cost?
We do not publish rates, because an honest figure depends on size, structure, complexity and the quality of what you provide. What we do publish is how the figure is built and where you have influence over it.
What happens after an enquiry?
Your enquiry reaches our audit partner. In an introductory call we establish what level of assurance your situation calls for and whether the engagement belongs with us.
If it does not — because you are subject to statutory audit, for instance — we say so immediately and help you think about the next step.
The firm
Led by a registered accountant
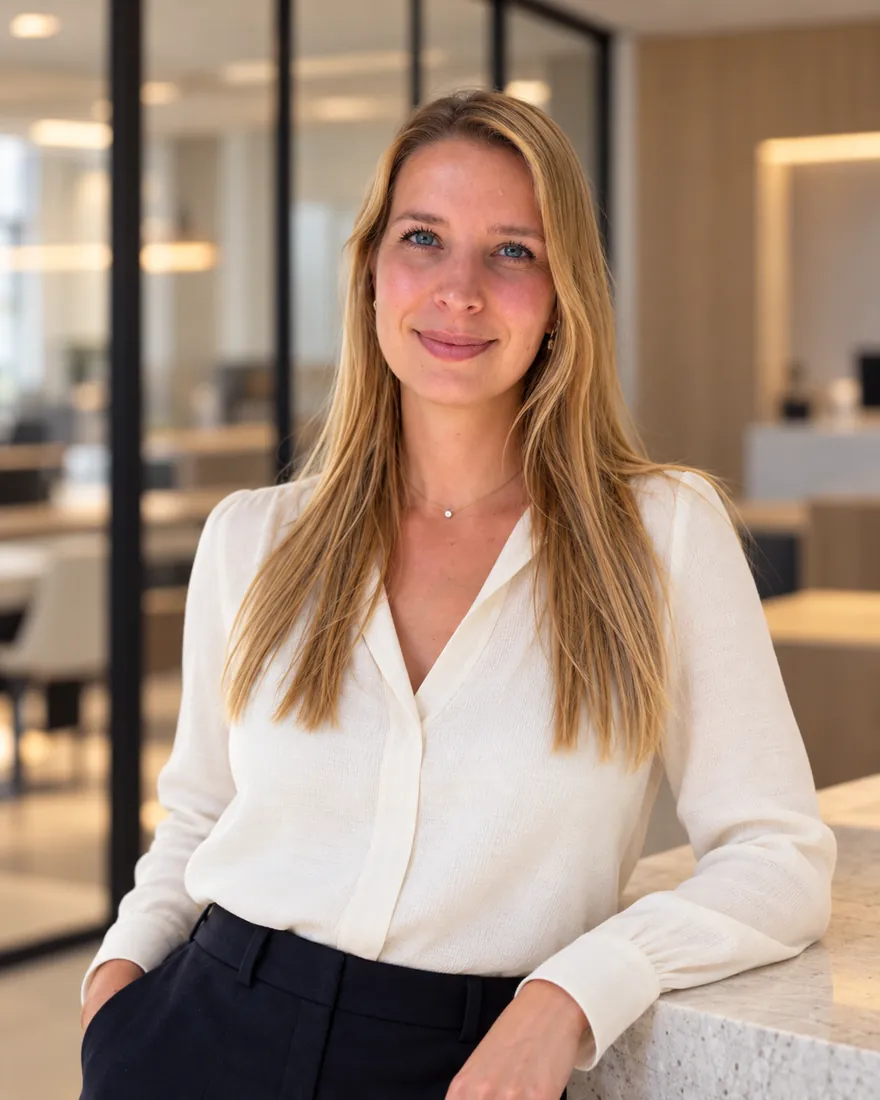
Sophie Terwindt RA is audit partner of The Working Paper and carries professional responsibility for every engagement the firm accepts. She reviews and she signs.
Trained at Deloitte on audits of multinational and listed companies, then engagement lead at mid-sized firms. She has also worked as a financial controller preparing records for audit — a perspective rarely found on this side of the table.
Contact
Start with what is actually needed.
Tell us who is asking for assurance and why. We will work out together which engagement fits — including when that is a lighter one than you expected.
request a call: Sophie Terwindt RA replies within one working day · call: for a quick question